
The mutual fund investor in India has never had a shortage of choices.
There are thousands of schemes, multiple categories, direct and regular plans, ETFs, index funds and, more recently, Specialised Investment Funds (SIFs).
The harder part often comes after the investment is made.
How much should go into equity? Which funds should be held together? When should one fund be reduced? When should a portfolio be rebalanced? And perhaps the most difficult question of all: what should an investor do when markets fall sharply?
The Securities and Exchange Board of India (SEBI) has now created a new route around this problem.
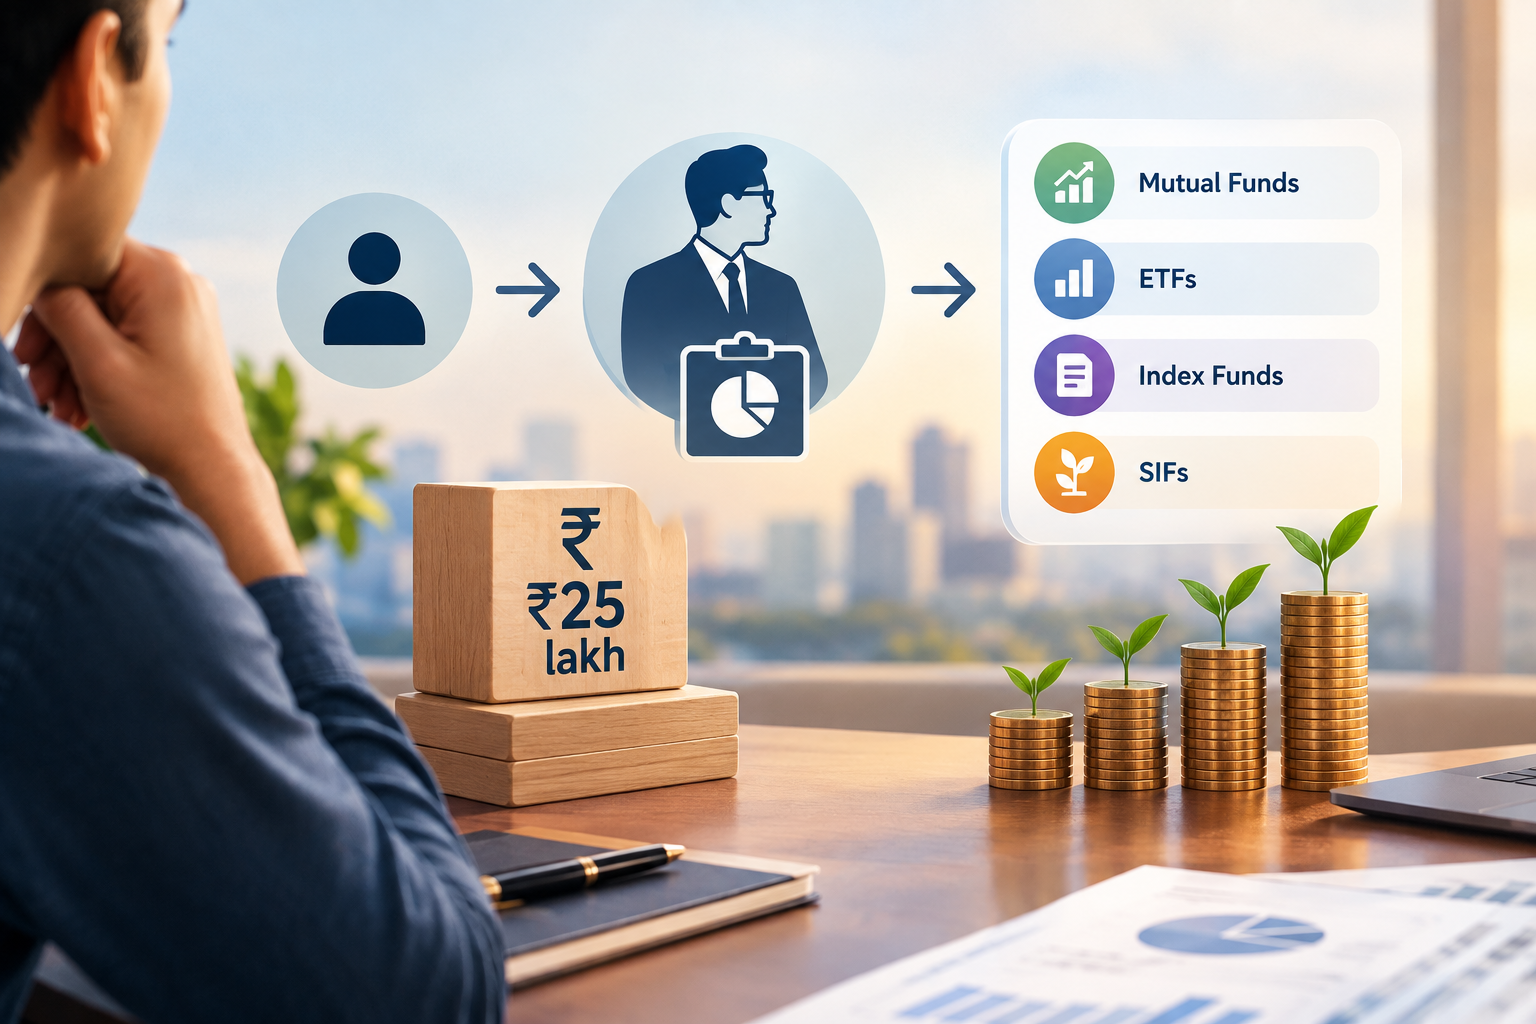
At its board meeting on 24 September 2026, SEBI approved the Portfolio Managers Route for Investing in Mutual Fund units, or PRIM. The framework will allow registered portfolio managers to manage client portfolios using direct plans of mutual funds, including ETFs, index funds and Specialised Investment Funds (SIFs) offered by Indian asset management companies. (Securities and Exchange Board of India)
The minimum investment has been set at ₹25 lakh.
That is half the ₹50 lakh minimum currently associated with conventional PMS.
For investors with ₹25 lakh or more who want professional portfolio management but do not want a portfolio built directly from individual stocks and bonds, PRIM creates a new middle ground.
But the ₹25 lakh number is only one part of the story.
What exactly is PRIM?
PRIM is essentially a mutual-fund-focused portfolio management route.
Under the framework, a portfolio manager can take an investor’s money and construct a portfolio using direct mutual fund plans, ETFs, index funds and SIFs. (Investment Guru India)
The important distinction is that the portfolio manager is deciding which funds to hold and how much to allocate to each, while the underlying mutual fund managers continue to make the investment decisions within their respective schemes.
That makes PRIM different from conventional PMS.
In a traditional PMS arrangement, the portfolio manager can directly construct a portfolio of permitted securities such as shares, bonds and other instruments. Under PRIM, the portfolio is built through mutual fund units and related fund products.
So, an investor is not handing over ₹25 lakh to a manager to pick individual stocks.
The manager is managing the fund portfolio.
That distinction matters.
Why has SEBI created a ₹25 lakh route?
The conventional PMS framework has generally been targeted at investors with at least ₹50 lakh.
PRIM cuts that entry point to ₹25 lakh, while keeping the portfolio within mutual fund-based products.
SEBI’s broader overhaul of the Portfolio Managers Regulations, 2020 is intended to develop the PMS industry, simplify compliance and consolidate the regulatory framework. The new 2026 regulations replace the existing framework. (Investment Guru India)
For the investor, however, the more interesting change is not simply the lower minimum.
It is the separation between product selection and portfolio management.
A person can already buy a direct mutual fund without paying a distributor commission. What PRIM adds is a regulated portfolio manager who can decide how those funds fit together, monitor the portfolio and make changes within the agreed strategy.
That addresses a problem many investors face after accumulating several mutual funds.
Buying a fund is relatively easy.
Managing five, eight or ten funds properly is another matter.
PRIM is not a new mutual fund product
This is perhaps the most important distinction for investors.
PRIM does not create a new category of mutual funds.
The underlying products remain mutual fund schemes, ETFs, index funds and SIFs.
The new layer is the portfolio manager sitting above those products.
For example, an investor could have ₹30 lakh under a PRIM arrangement. Instead of deciding independently how that money should be distributed across equity, debt, index funds or SIFs, the portfolio manager would construct the portfolio according to the investment approach agreed with the client.
The investor therefore outsources the portfolio-level decisions.
The underlying fund managers do not change.
This is why PRIM should not be confused with handing over money to someone who directly buys stocks on the investor’s behalf.
The ₹25 lakh minimum is only the entry ticket
SEBI has prescribed a minimum ticket size of ₹25 lakh for PRIM.
There are also requirements on the portfolio manager.
A PRIM portfolio manager must have a minimum net worth of ₹2 crore. The principal officer must meet specified qualification and experience requirements, including graduation/CFA/CA, two years of experience in the securities market and a simplified NISM certification. (Investment Guru India)
For investors, these requirements matter because PRIM is not simply a new label that any investment platform can attach to a mutual fund portfolio.
It sits inside SEBI’s portfolio management framework.
An existing portfolio manager can offer PRIM through a separate investment approach. An entity intending to operate only within the securities permitted under PRIM can apply for a new registration. (Investment Guru India)
What can a PRIM portfolio invest in?
SEBI’s framework allows PRIM portfolios to use:
- Direct plans of mutual funds
- Exchange-traded funds
- Index funds
- Specialised Investment Funds
The products must be offered by Indian asset management companies. (Investment Guru India)
The inclusion of SIFs is significant.
SIFs were introduced to sit between conventional mutual funds and more sophisticated investment products, with a higher minimum investment requirement and greater flexibility in strategy.
Under the latest SEBI framework, an investor using PRIM could therefore have a portfolio that combines conventional mutual funds with ETFs, index funds and eligible SIF strategies, depending on the portfolio manager’s approach.
That gives managers more room to build portfolios around an investor’s risk profile and objectives.
It does not, however, remove investment risk.
The 1% fee needs to be understood properly
SEBI has capped the fixed management fee at a maximum of 1% of the client’s AUM under PRIM. A performance-based fee model is also permitted. (Investment Guru India)
At the maximum fixed fee, a ₹25 lakh portfolio would mean ₹25,000 a year in management fees, before considering other applicable costs.
But there is an important detail here.
The 1% PRIM fee is not the same thing as the total cost of owning the underlying investments.
The mutual fund schemes themselves have expenses. Those costs continue to apply according to the structure of the underlying schemes.
So an investor comparing PRIM with doing a direct mutual fund portfolio independently should not look only at the headline 1% fee.
The real question is what the investor receives in return for that additional layer of portfolio management.
SEBI has also put a limit on affiliated AMCs
There is another investor-protection provision that deserves attention.
PRIM portfolios will have a 25% cap on investments in schemes of affiliated, group or associate asset management companies. (Investment Guru India)
That prevents a portfolio manager from simply concentrating the client’s money heavily in funds connected to its own group.
For an investor, this is worth checking when evaluating a PRIM provider.
The question is not only which funds the manager recommends.
It is also how the portfolio is constructed, how much concentration exists across fund houses, what triggers a rebalance and whether the strategy has clear rules around risk.
What happens to exit loads?
SEBI has provided for a waiver of exit-load provisions under PRIM. (Investment Guru India)
That is another difference investors should understand before comparing a PRIM portfolio with a self-managed mutual fund portfolio.
In a normal mutual fund investment, an investor may face an exit load when units are redeemed within the specified period.
Under the PRIM framework, SEBI has specifically provided for a waiver of exit-load provisions.
The exact implementation and contractual details will still matter when portfolio managers begin offering the service.
PRIM and MFD activities must remain separate
SEBI has also addressed a potential conflict between distribution and portfolio management.
The regulations require segregation of activities and clients between Mutual Fund Distributor (MFD) and PRIM, except for accredited investors. (Investment Guru India)
That distinction is important because distribution and portfolio management involve different roles.
An MFD distributes mutual fund products.
A PRIM portfolio manager is responsible for managing the client’s portfolio under the portfolio management framework.
For investors, understanding which capacity they are dealing with can prevent confusion around fees, advice, product selection and responsibility.
PRIM versus doing it yourself
This is where the new route becomes interesting.
An investor with ₹25 lakh can already build a direct mutual fund portfolio without using PRIM.
There is no requirement to use a portfolio manager simply because the investor crosses the ₹25 lakh threshold.
The difference is who makes the portfolio-level decisions.
DIY mutual fund investing:
The investor selects funds, decides allocation, monitors performance and handles rebalancing.
PRIM:
A registered portfolio manager makes those portfolio-level decisions within the agreed investment strategy.
Traditional PMS:
A portfolio manager manages a broader portfolio of permitted securities, subject to the PMS framework, with the conventional minimum investment threshold of ₹50 lakh.
PRIM therefore creates another choice for investors who want professional management but prefer their portfolio to remain within fund-based products.
The bigger change may be behavioural
For investors, the most interesting part of PRIM may not be the product list.
It may be what happens when markets become uncomfortable.
An investor can select a good mutual fund and still damage long-term returns by repeatedly changing funds, chasing recent performers, stopping SIPs during corrections or holding too many overlapping schemes.
Professional portfolio management is partly an attempt to remove some of those decisions from the investor’s hands.
But there is no guarantee that professional management will produce better returns.
A portfolio manager can choose the wrong allocation. A strategy can underperform. Fees can reduce returns. And a professionally managed portfolio can still fall when markets fall.
PRIM changes who manages the decisions.
It does not change the underlying nature of market risk.
A ₹25 lakh portfolio can still be poorly managed
This is the part investors should not lose sight of amid the attention around the new route.
₹25 lakh is a large amount of money for most households.
Putting it into a professionally managed structure does not automatically make the portfolio suitable.
An investor should still understand the investment approach, asset allocation, risk level, costs, benchmark, rebalancing rules and the conditions under which the manager can change the portfolio.
The word “professional” should not replace due diligence.
Nor should a lower entry threshold be mistaken for lower risk.
What PRIM could mean for India’s wealth market
SEBI’s move comes at a time when India’s mutual fund industry has expanded far beyond the traditional image of a few large equity and debt schemes.
Investors now have access to index strategies, ETFs, thematic funds, passive products and SIFs.
The challenge is increasingly moving from access to selection and portfolio construction.
PRIM is SEBI’s response to that shift.
The regulator is effectively creating a regulated bridge between the mutual fund ecosystem and portfolio management.
At ₹25 lakh, that bridge reaches a wider pool of affluent investors than conventional PMS.
Whether investors actually benefit will depend on how portfolio managers use the new freedom, what fee structures emerge and whether the portfolios offered are genuinely differentiated from what investors could build themselves.
For now, the change is clear.
Mutual funds remain the underlying investment products. PRIM adds professional portfolio management around them.
And for an investor with ₹25 lakh or more, that is a new choice that did not exist in this form before SEBI’s September 2026 decision.
What investors should remember
PRIM does not mean SEBI has created a new mutual fund category.
It is a portfolio-management route for mutual fund investments.
The minimum ticket is ₹25 lakh. Portfolios can use direct mutual funds, ETFs, index funds and SIFs. The fixed management fee is capped at 1% of AUM, while performance-linked fees are permitted. Affiliated AMC exposure is capped at 25%. Portfolio managers also have to meet specified net-worth, qualification and regulatory requirements. (Investment Guru India)
For investors, the decision will ultimately come down to one practical question:
Is paying for someone to manage the portfolio worth it when the underlying mutual funds can already be bought directly?
That answer will depend less on the ₹25 lakh entry ticket and more on the quality of the portfolio construction, discipline, transparency and costs attached to the service.
Source: SEBI Board decisions dated 24 September 2026; latest reporting from Mint, Moneycontrol and Economic Times. (Securities and Exchange Board of India)
Nevesh Editorial Note
The new PRIM route is significant because it changes the way investors can access professional portfolio management, not because it makes mutual fund investing inherently better. Investors who already have a disciplined asset-allocation strategy may not need another layer between themselves and their funds. For others, the value could lie in having someone responsible for portfolio construction and rebalancing. The fee, process and investment discipline will matter far more than the ₹25 lakh headline.
Risk Disclaimer: This article is for educational and informational purposes only and should not be treated as investment advice. Mutual fund investments are subject to market risks. Investors should read all scheme and portfolio-management documents carefully and assess costs and suitability before investing.